Movies
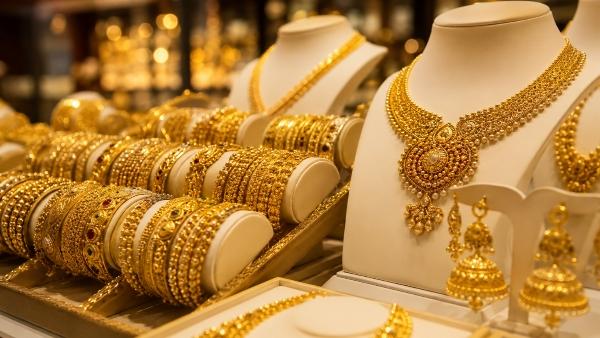
India's gold demand declined by 29% during the July–September quarter compared with the corresponding period last year, as prices surged by nearly 45%, according to the latest report by the World Gold Council (WGC). Demand fell from 229.8 tonnes to 162.5 tonnes, although its overall value increased by 3% from ₹2,35,090 crore to ₹2,41,900 crore. The council attributed the decline to higher gold prices, increased import duties and the rupee's depreciation against the US dollar, which made gold more expensive in India than in international markets. It also flagged concerns over rising gold smuggling and lower exchanges of old jewellery. Jewellery demand dropped 20% from 125 tonnes to 99.9 tonnes, while purchases of gold bars and coins fell 40% from 91.6 tonnes to 55 tonnes. Investments in gold exchange-traded funds (ETFs) declined 50% to 5.3 tonnes, and the exchange of old gold fell 12% to 19.2 tonnes.
India's official net gold imports declined 46% from 211.9 tonnes to 114.1 tonnes during the quarter. However, unofficial imports reportedly surged 1,500% from 3 tonnes to 50 tonnes, citing estimates by consultancy firm Metals Focus. The average international gold price rose from $3,457 to $4,262 per ounce, while the price of 10 grams of pure gold in India increased from ₹1,02,287 to ₹1,48,891, excluding import duty and GST. Globally, gold demand declined by 1% to 1,369 tonnes, but its value increased by 22% to $188 billion. WGC Regional CEO Sachin Jain said Indians continue to consider gold a long-term investment despite price fluctuations. He added that the moderation in prices towards the end of September encouraged some consumers to resume postponed purchases, with sales performing particularly well in South India amid the wedding and festive seasons. The WGC expects India's total gold demand for the year to range between 625 and 675 tonnes.
Comments (0)
No comments yet
Be the first to comment!