General
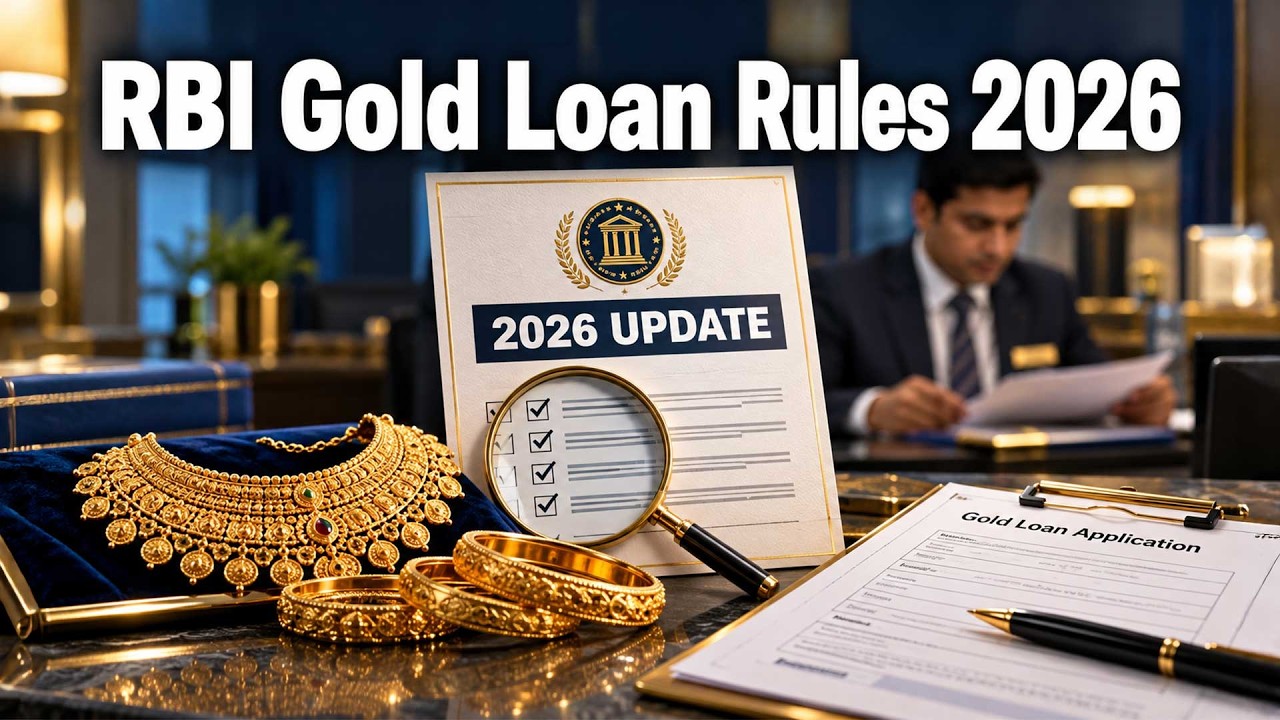
Gold loans are a popular borrowing option in India, as people can pledge their gold jewellery to meet personal and financial needs. Since the loan is secured against gold, the interest rates are generally lower than those of unsecured personal loans. The Reserve Bank of India (RBI) introduced revised guidelines on June 5, 2025, to improve transparency in gold lending and protect borrowers' rights. Under these guidelines, the loan-to-value (LTV) ratio varies depending on the loan amount.
For loans up to ₹2.5 lakh, borrowers can get up to 85% of the value of the pledged gold. For loans above ₹2.5 lakh and up to ₹5 lakh, the limit is 80%, while loans exceeding ₹5 lakh are subject to a 75% limit. For example, if the gold pledged is valued at ₹1 lakh, a borrower may be eligible for a loan of up to ₹85,000 under the first category, subject to the lender's assessment and other conditions. The guidelines also state that bullet-repayment gold loans taken for consumption purposes must have a maximum tenure of 12 months. Under this repayment method, the borrower pays the principal and interest together at the end of the loan period. If the borrower fails to repay, the lender can auction the pledged gold after providing prior information and notice to the borrower.
Comments (0)
No comments yet
Be the first to comment!