Sports
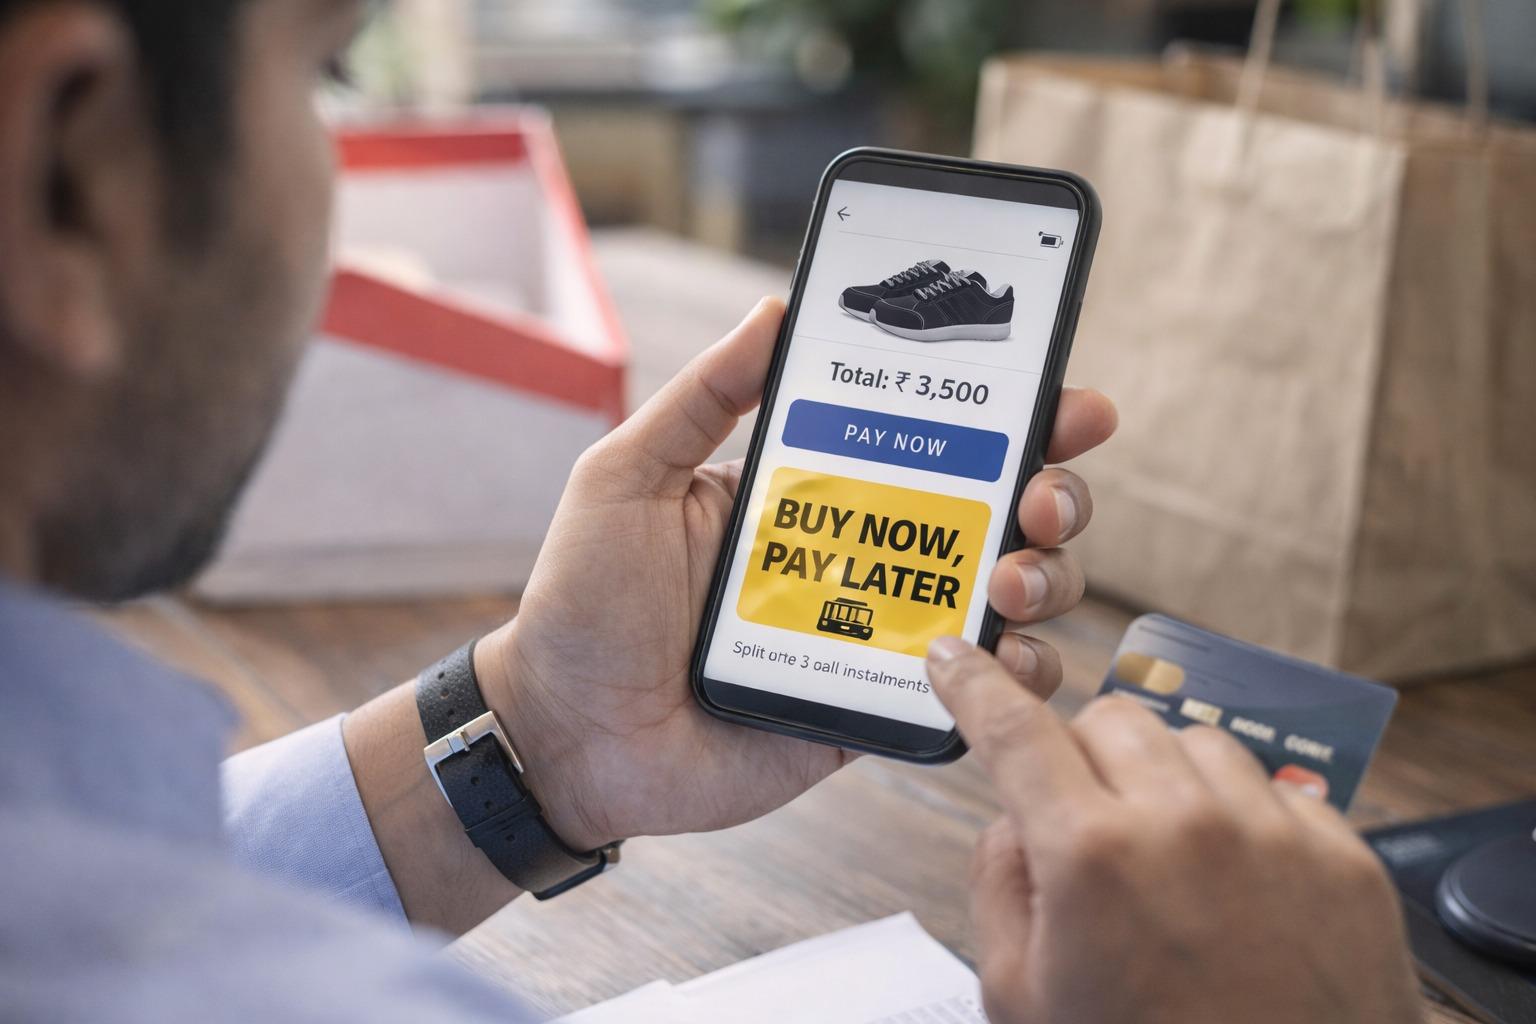
Attractive advertisements such as ‘Buy Now, Pay Later’, ‘No-Cost EMI’, ‘Instant Pre-Approved Loans’ and ‘Lifetime Free Credit Cards’ often tempt consumers into spending beyond their means. The convenience of purchasing expensive products without paying the full amount upfront can create a false sense of affordability. Growing consumerism and social comparisons are also encouraging people to replace perfectly usable phones, cars and other possessions simply to keep up with changing trends. However, every purchase made on credit creates a future financial obligation. When people accumulate multiple EMIs without assessing their repayment capacity, unexpected medical expenses, job insecurity or other emergencies can push them into financial distress. In some cases, borrowers end up taking fresh loans just to repay existing ones, trapping themselves in a cycle of debt.
The concept of ‘No-Cost EMI’ also deserves careful scrutiny, as the actual cost of borrowing may be recovered through processing fees, upfront charges or other hidden expenses. A smaller monthly instalment does not necessarily mean a cheaper purchase. Similarly, paying only the minimum amount on a credit card bill can result in substantial interest charges on the outstanding balance. While loans for a house, education or business may support long-term financial growth, unnecessary borrowing driven by social pressure can become a financial burden. True financial freedom is not about being able to buy everything, but about having sufficient savings to meet essential needs and handle unexpected difficulties. Delaying impulsive purchases, understanding the total cost of credit and borrowing only when necessary can help protect financial stability. A peaceful life supported by savings and responsible spending is far more valuable than a lifestyle maintained through endless EMIs.
Comments (0)
No comments yet
Be the first to comment!