General
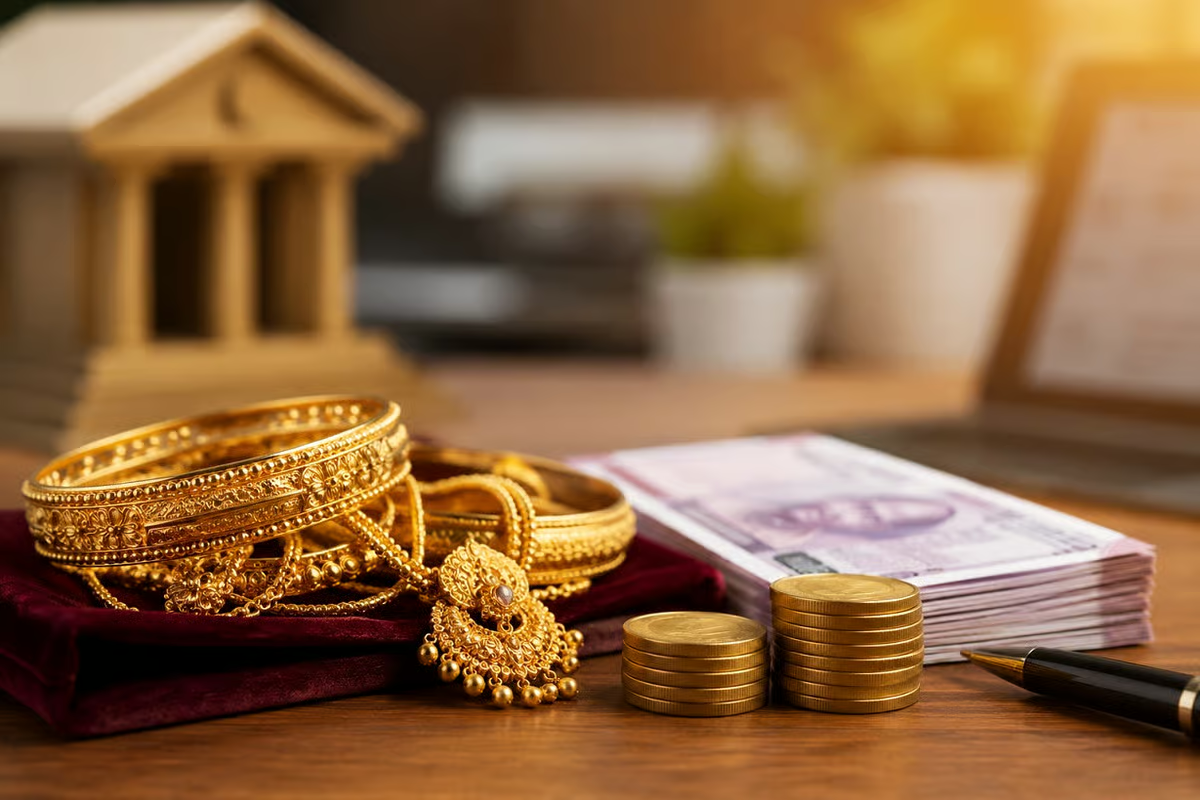
The gold loan market in India is facing growing pressure as banks and non-banking financial companies (NBFCs) encounter difficulties in recovering loans backed by gold jewellery. Although repayment defaults have not yet reached an alarming level across the market, financial institutions are becoming cautious about the risks. Piramal Finance has reportedly stopped offering fresh loans to customers who have failed to repay their existing gold loans, while Bajaj Finance has announced plans to discontinue short-term gold loans.
The sharp rise in gold and silver prices over the past year, which continued until January, encouraged lenders to expand their gold loan portfolios. By August of the current financial year, banks had disbursed gold loans worth ₹5.6 lakh crore, an increase of 83% compared with the same period last year. NBFCs had extended gold loans worth ₹3.6 lakh crore, marking a 69% rise. However, the article reports that precious metal prices have fallen by as much as 50% from their January peaks, putting pressure on borrowers and lenders. Piramal Finance stated that 15% to 23% of its gold loans remained unpaid even 90 days after their due dates, prompting the company to restrict fresh lending to such customers.
The Reserve Bank of India (RBI) had introduced guidelines in June last year to manage risks in the gold loan sector. Under the rules, lenders can provide loans of up to 85% of the gold's value for amounts up to ₹2.5 lakh, up to 80% for loans between ₹2.5 lakh and ₹5 lakh, and up to 75% for loans above ₹5 lakh. These guidelines came into effect in April this year, leading to some moderation in gold lending. Meanwhile, rating agency ICRA estimates that the total gold loans issued by banks and NBFCs in India could reach ₹30 lakh crore by March 2028, highlighting the sector's rapid expansion and the importance of careful lending practices.
Comments (0)
No comments yet
Be the first to comment!